
The End of the 40-Year Bull Run
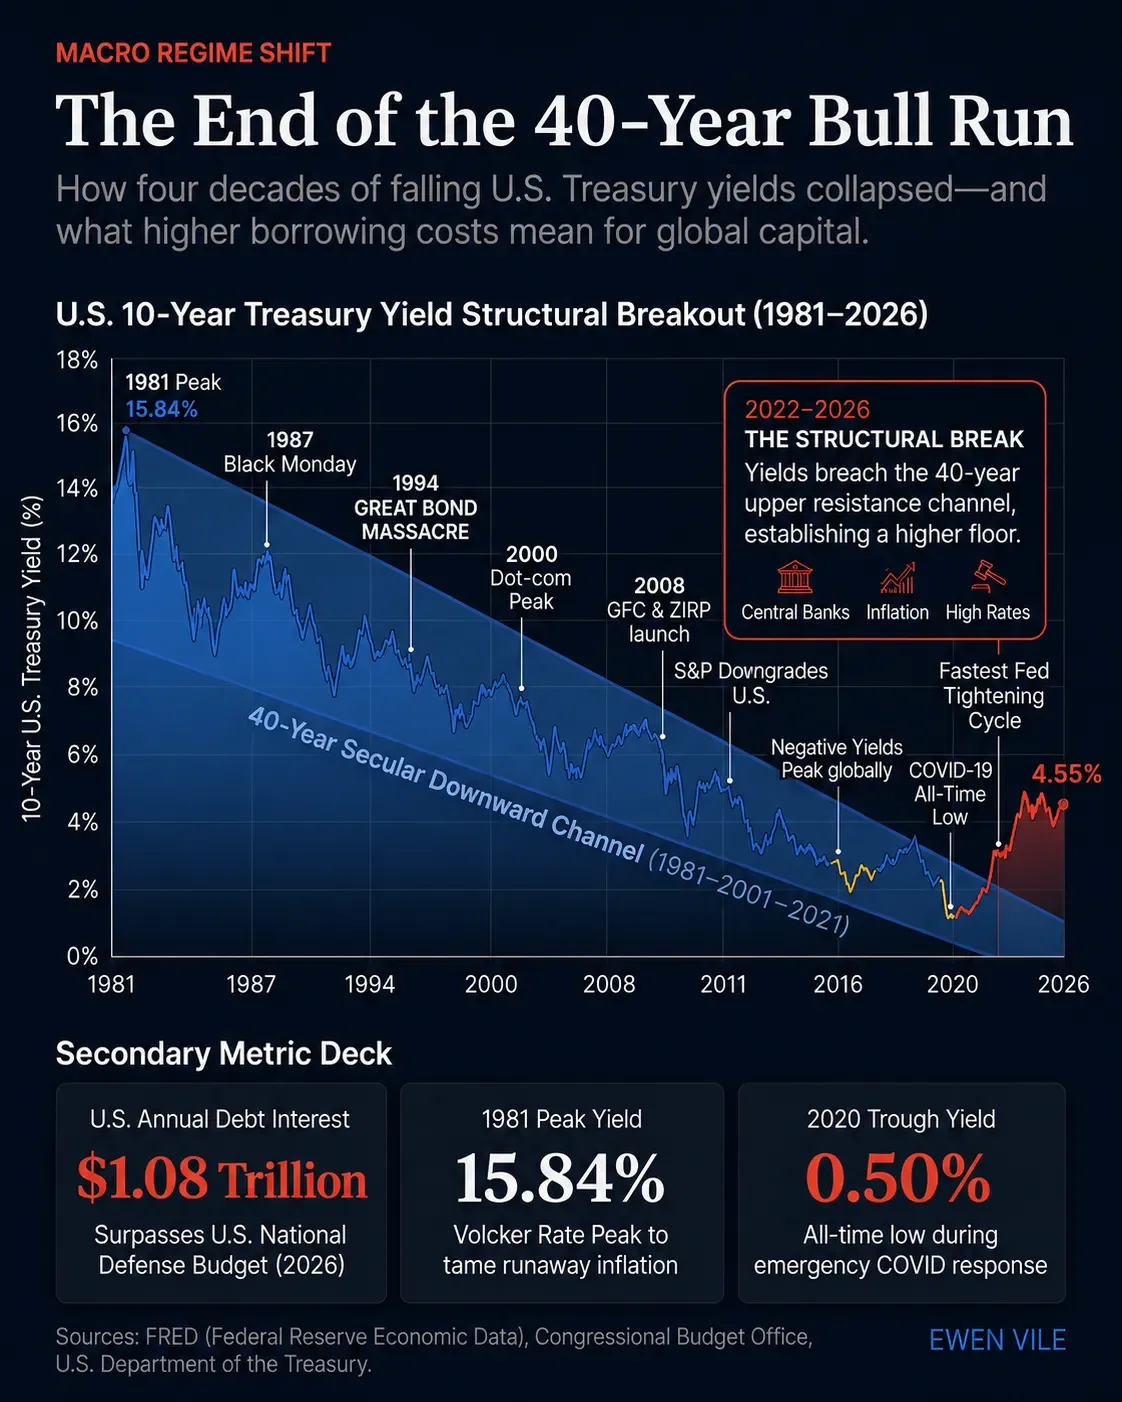
For four decades (1981–2021), the global financial system operated under a single dominant macro trend: continuously falling interest rates. From Paul Volcker’s 15.84% inflation peak in 1981 down to the emergency 0.50% COVID-era trough in 2020, cheap capital anchored stock valuations, mortgage rates, and sovereign debt issuance. Between 2022 and 2026, that multi-decade secular downward channel officially collapsed. Driven by persistent inflation pressures and aggressive monetary tightening, U.S. 10-Year Treasury yields breached their 40-year upper resistance trendline, establishing a higher structural floor. As interest costs rise, U.S. annual net debt interest service has surged past $1.08 Trillion—officially surpassing national defense spending and reshaping global capital flows. KEY METRICS & HIGHLIGHTS: • U.S. Annual Debt Interest: $1.08 Trillion (Surpasses National Defense Budget) • 1981 Peak Yield: 15.84% (Volcker Rate Peak to tame runaway inflation) • 2020 Trough Yield: 0.50% (All-time low during emergency COVID response) • 2026 Current Yield Level: 4.55% (Structural breakout above 40-year channel)
